

Best Budget

- 0.00 Reviews
- 0.0
- Downloads
- 10,000+
Our take on Best Budget from Appgk
Managing money sounds simple until everyday spending starts arriving from several directions at once. I approached Best Budget as a practical finance app rather than a complete banking replacement, and that distinction matters. Its purpose is to help me see spending, plan a budget, reduce debt, and work toward savings in one place. That makes it appealing for someone who wants a clearer routine without immediately committing to a complicated financial system.
CREXIN Technologies developed the app, which is free to install and aimed at Everyone. It is available for Android devices running version 8.0 or later, and the current release is 2.1.4. Optional in-app purchases range from $6 to $96 per item, so I would treat the free entry point as a chance to test the workflow before paying for anything.
How Best Budget feels during everyday use
A quick start, but only if I keep the setup focused
The first useful step is not entering every historical transaction. I would begin with the accounts or spending areas that affect the next few weeks: housing, food, transport, subscriptions, debt payments, and savings. This keeps the initial experience manageable and gives the budget a purpose immediately. Trying to reconstruct an entire financial year before using the app would make the process feel like paperwork instead of a helpful habit.
Because the app is built around tracking spending and setting budgets, its perceived speed depends partly on how much information I choose to maintain. A short list of active categories should feel easier to navigate than a highly detailed system with dozens of small labels. That is an important practical trade-off: more categories can reveal patterns, but too many can slow down the human part of budgeting because every purchase becomes a classification decision.
Best Parts of Best Budget
Things to Keep in Mind About Best Budget
I would also avoid treating the first budget as a final answer. A realistic starting plan should reflect what I normally spend, not an ideal version of my life. After a week or two, I could adjust categories that are consistently too tight or too generous. This approach makes the app more useful than a budget created once and then ignored.
What happens when spending gets busy
The most demanding moments are likely to come when several purchases need attention at once. A grocery trip, a fuel payment, a bill, and a small online order may all arrive on the same day. In that situation, the app’s value is less about dramatic automation and more about reducing confusion. I would enter or review transactions in batches, then check whether the category totals still match the plan.
News and Features Related to Best Budget

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo

News
Moovit Review: A More Reliable Way to Navigate Everyday Transit

News
Mastering Screen Recorder - XRecorder: Pro Tips for Mobile Video
A useful workflow is to separate recording from analysis. During a busy day, I would capture the purchase with enough detail to recognize it later rather than stopping to study the entire budget. In the evening, I would review the day’s entries together. This avoids turning every payment into a long interruption and makes it easier to notice duplicate entries or spending assigned to the wrong category.
Debt management is another area where a calm workflow matters. I would list required payments first, then decide what extra amount can realistically go toward a balance. The app can support the planning side of that decision, but it cannot make an unaffordable payment affordable. Anyone using it for debt should leave room for essentials and unexpected costs instead of directing every spare amount to repayment.
Don't want to read the full review?
Stability is also about recoverability
A finance app earns trust gradually. I want to know that I can return after a few days away, understand where I stand, and continue without rebuilding the whole plan. Best Budget is most convincing when used as a regular checkpoint rather than a one-time calculator. A short weekly review can reveal whether spending is drifting before the end of the month makes the problem obvious.
Recovery is especially important when I make a mistake. If a transaction is placed in the wrong category, I would correct it as soon as I notice rather than abandoning the budget. The practical lesson is to keep categories understandable and avoid creating a structure that becomes difficult to repair. A budget that is slightly broad but maintained consistently is more useful than a perfect-looking budget that takes too much effort to update.
Screenshots
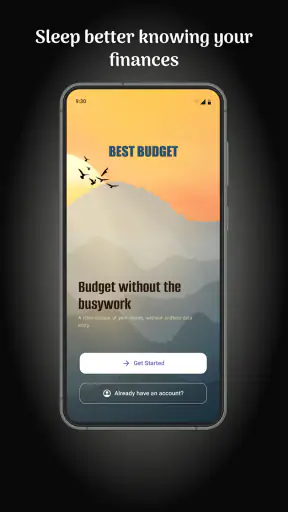
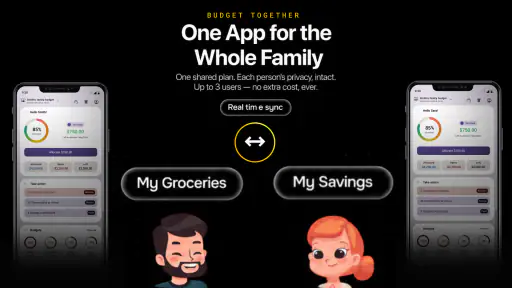
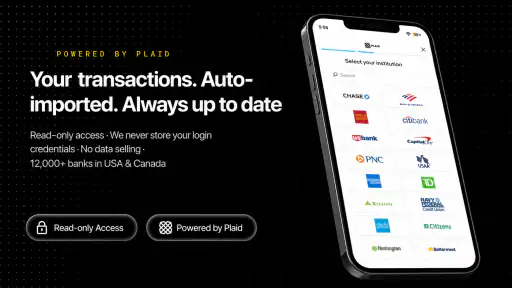
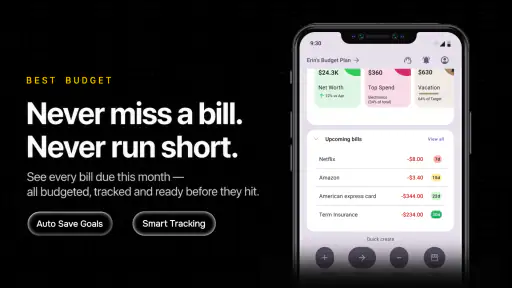
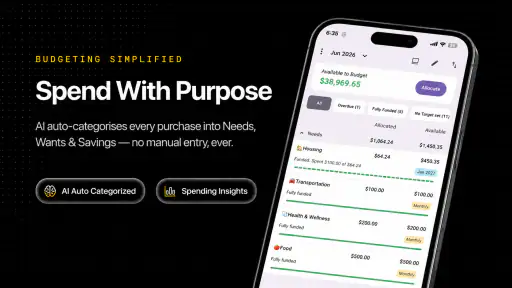
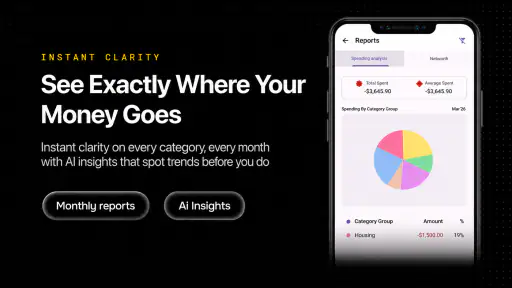
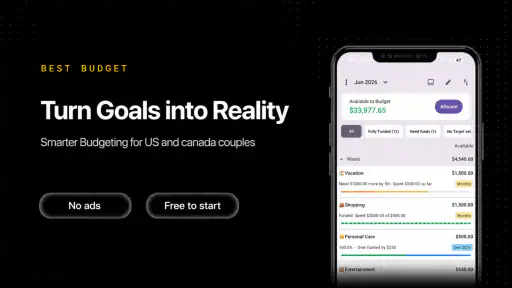
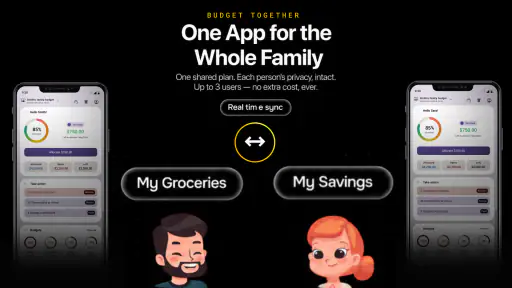
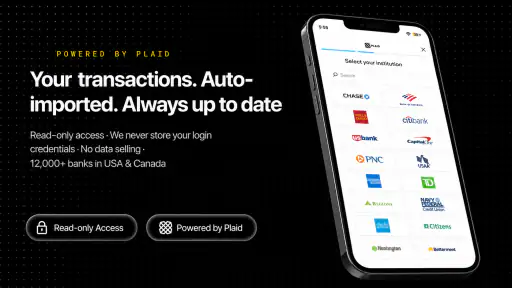
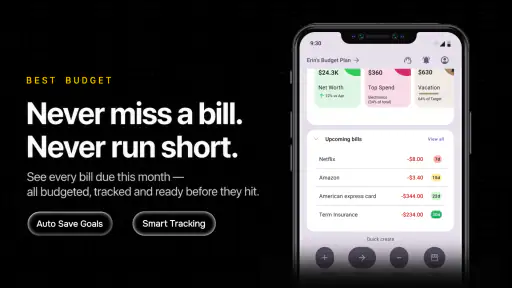
I would also keep a personal note of major balances and planned payments outside the app while establishing a routine. That is not a criticism of this particular product; it is sensible protection whenever financial information is being organized digitally. It gives me a reference point if I change devices, forget a detail, or need to reconstruct a plan.
Resource demands and older phones
The Android requirement is modest, with support beginning at version 8.0. That makes the app approachable for people who are not using a recent phone. Still, an older operating system can affect the overall experience through the device itself: limited storage, slower multitasking, or a battery that is already under strain can make any finance app feel less responsive.
I would use it on an older device with a simple routine rather than keeping many other demanding apps open at the same time. Budget tracking generally benefits from short, deliberate sessions, so there is little reason to leave it running continuously. Closing unused apps, keeping adequate storage available, and installing system updates that the phone supports are more useful than expecting the finance app to compensate for a heavily constrained device.
On a newer phone, the main resource consideration is probably not raw power but attention. Notifications, frequent checking, and constant category adjustments can turn a helpful budget into another source of stress. I prefer setting a small number of review moments and using those sessions to make decisions. The app should support financial awareness, not encourage me to stare at totals after every purchase.
Where the free model fits
Best Budget is free to install, which lowers the risk of trying it. That is valuable for someone who has never maintained a budget and is unsure whether a dedicated app will become part of their routine. The presence of optional purchases means I would inspect what each paid item unlocks before spending money. A paid upgrade only makes sense if it removes a real obstacle in my own workflow.
I would not subscribe or purchase simply because the app offers more possibilities. First I would test whether I can record spending consistently, understand the category totals, and use the debt or savings planning in a way that changes my decisions. If the basic routine does not stick, extra tools will not solve the underlying problem.
The app has passed the ten-thousand-install mark, which suggests that it is not an entirely untested idea, but I would still judge it by personal fit rather than popularity. A smaller finance app can be a good choice when its structure is easier for me to maintain. Conversely, someone who needs mature synchronization, extensive reporting, or a long-established ecosystem may prefer a more established alternative.
Best Budget compared with familiar alternatives
The usual alternative is a spreadsheet. A spreadsheet gives me complete control over formulas, categories, and layout, but it also asks me to design and maintain the system. Best Budget is the better starting point if I want a ready-made budgeting environment and do not want to build calculation rules myself. The spreadsheet remains stronger for unusual household arrangements, custom forecasting, or people who enjoy inspecting every formula.
Another alternative is a banking app’s built-in spending view. That can be convenient because transactions may already be connected to the financial institution, while a dedicated budgeting app can encourage me to think across spending, debt, and savings rather than looking only at one account. The trade-off is convenience versus deliberate control. I would choose the banking view for quick awareness and Best Budget when I want a separate plan that reflects my goals.
Envelope-style budgeting is a third comparison. Its strength is discipline: each category has a clear limit, and spending decisions become tangible. Best Budget can suit someone who wants that planning mindset without using physical envelopes, especially when the goal is to combine ordinary spending with debt reduction and savings. Someone who needs strict, highly specialized envelope rules may find a dedicated envelope tool more natural.
A realistic month with the app
Imagine I receive income at the beginning of the month and have rent, utilities, transport, groceries, a credit payment, and a savings target competing for the same money. I would begin by assigning the unavoidable costs, then set a practical food and transport limit based on my normal routine. The remaining amount would be divided between debt progress, savings, and flexible spending rather than pretending that every month is perfectly predictable.
After the first week, I would check whether groceries are consuming too much of the planned amount. If they are, I would look for the cause instead of simply lowering the limit: an unusual purchase, frequent convenience meals, or a category that was defined too narrowly. That diagnosis is where a budgeting app becomes useful. The number itself is not the solution; understanding the behavior behind it is.
Near the middle of the month, I would review upcoming debt payments and savings contributions before making optional purchases. If an unexpected expense appears, I would adjust the plan openly rather than hiding it in an unrelated category. At the end of the month, I would compare the plan with reality and carry forward only the lessons that matter. This makes the app a decision aid, not a scoreboard designed to make me feel guilty.
Small techniques that improve the experience
One technique I find valuable is creating categories around decisions rather than store names. “Eating out” tells me something about behavior; separate categories for every restaurant usually do not. This keeps the budget readable and makes it easier to decide where to cut when debt or savings goals need attention.
A second technique is to give irregular expenses their own place in the plan. Annual renewals, gifts, repairs, and seasonal costs can make a monthly budget look successful until they suddenly arrive. I would set aside a small planned amount for these items instead of treating them as failures. The result is a more stable budget and fewer emergency adjustments.
A third is to use debt and savings goals together rather than treating them as competing identities. A small, consistent savings reserve can prevent a minor surprise from going straight onto a credit balance, while debt payments still need enough priority to make progress. Best Budget is useful here because its purpose reaches beyond recording yesterday’s purchases; it encourages me to connect today’s spending with the next financial decision.
There is also a human limitation worth emphasizing. Any app can make tracking look organized while the underlying figures are incomplete. Cash purchases, shared household spending, refunds, and transfers need careful treatment. I would review those entries deliberately, especially if more than one person uses the same money. A polished total is not automatically an accurate total.
Who should use it, and who should skip it
I would recommend Best Budget to a beginner who wants one focused place to establish spending limits, think about debt, and build a savings habit. It can also suit someone who has tried a spreadsheet but found the maintenance too tedious. The free installation makes experimentation sensible, and the Everyone age rating keeps the app broadly approachable.
I would be more cautious if I needed automatic financial aggregation, advanced investment analysis, business bookkeeping, or highly detailed household collaboration. Those needs call for tools designed specifically around connected accounts, investment portfolios, or multi-user accounting. Best Budget’s central value is personal budgeting discipline, not replacing every financial service.
It may also be the wrong choice for someone who dislikes manual financial review entirely. A budgeting app cannot make meaningful decisions if I refuse to check categories, correct mistakes, or revisit goals. In that case, a simpler bank summary might be less ambitious but more likely to be used. The best tool is the one that fits the user’s willingness to maintain it.
My performance verdict
From a performance perspective, I would frame Best Budget as a focused, moderate-demand finance companion rather than an app that needs powerful hardware. Its support for Android 8.0 or later makes it accessible to older devices, while short review sessions should keep resource use and attention demands reasonable. The more important test is whether the workflow remains understandable when spending becomes irregular or a budget needs correction.
Its strongest quality is the connection between everyday tracking and longer-term intentions. I can use the same budgeting habit to identify overspending, plan debt payments, and protect savings. The main friction is that the quality of the result depends on accurate, consistent input, and the optional purchase range means I should evaluate paid additions carefully instead of assuming they are necessary.
The best reason to try it is not that it promises to fix money automatically, but that it can make my financial choices visible enough to change. I would install it if I wanted a straightforward starting point and was prepared to review my spending regularly. I would skip it in favor of a more specialized tool if connected accounts, advanced reporting, or complex shared finances were essential. For a person seeking a practical budgeting routine on an Android phone, Best Budget is worth testing with a small, realistic plan before expanding into more ambitious goals.
CREXIN Technologies has positioned the app in a useful space between a blank spreadsheet and a narrow bank summary. With more than ten thousand installs and a current version of 2.1.4, it offers a clear entry point for personal finance organization. My final advice is simple: begin with the next month, keep categories readable, record honestly, and judge the app by whether it helps me make better decisions when real spending starts to compete with my plans.
Best Budget FAQ
What is Best Budget, and what can I use it for?
Best Budget is a personal finance app designed to help you organize income, expenses, bills, and spending habits in one place. After setting up your financial categories and budget limits, you can record transactions and review where your money goes. It is useful for everyday expense tracking, planning monthly budgets, and developing better saving habits.
Is Best Budget suitable for beginners who have never used a budgeting app?
Yes, Best Budget is generally suitable for beginners because its main purpose is to make personal finance management easier to understand. New users can start by entering their income, creating common expense categories, and adding transactions as they occur. However, the usefulness of the app depends on consistent updates, so users should be prepared to record purchases regularly.
Does Best Budget connect directly to my bank accounts or cards?
Before downloading, users should check the current version and regional availability because account synchronization features can vary by platform, country, and subscription plan. If Best Budget does not support your bank, you may need to enter transactions manually. Manual tracking offers more control and privacy, but it requires additional effort compared with automatic financial-data imports.
Is my financial information safe when using Best Budget?
Budgeting apps may handle sensitive information, so it is important to review Best Budget’s privacy policy, permissions, storage practices, and security options before adding personal data. Avoid entering unnecessary account details, use a strong device passcode, and enable any available app lock or biometric protection. You should also download the app only from an official store.
Is Best Budget free, or does it require a subscription?
The cost of Best Budget may depend on the version available for Android or iOS and on the features included in the current release. Some functions may be free, while advanced tools could require a one-time purchase, subscription, or contain advertising. Check the app-store listing for the latest pricing, trial terms, renewal conditions, and cancellation instructions before starting.











